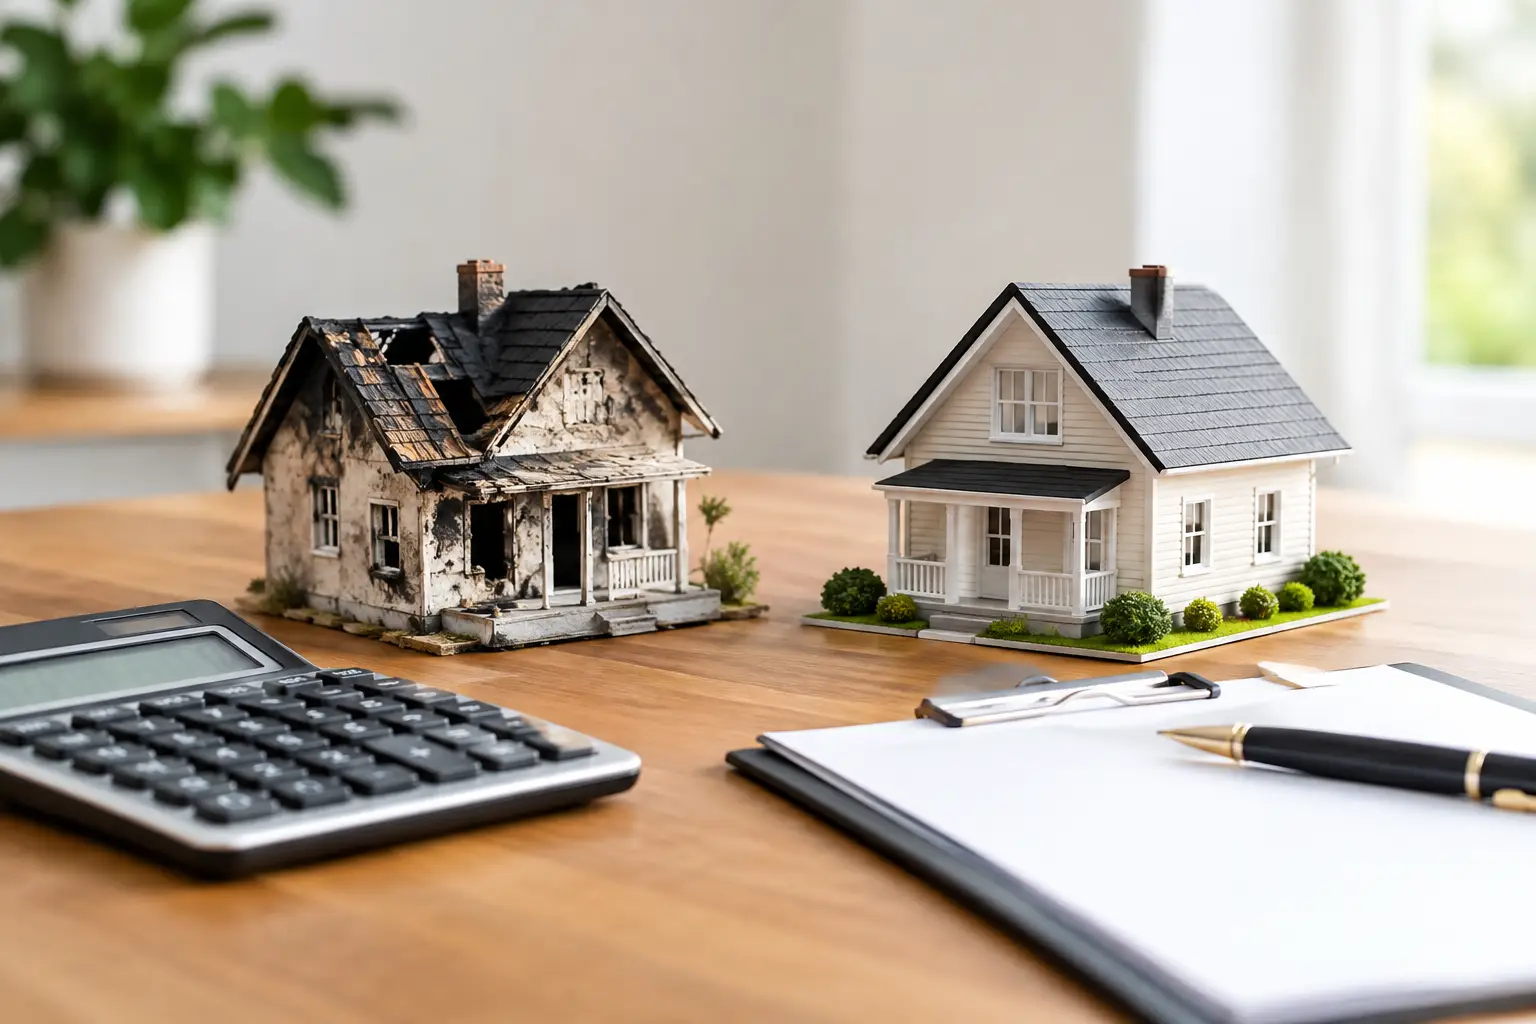
A fire damages the roof, electrical system, and tenant improvements in a commercial building. The policy limit may look substantial on paper, but the real question arrives when the claim is adjusted: will the policy pay what it costs to restore the property now, or subtract for age and wear? That is the practical difference behind replacement cost versus actual cash value, and it can materially affect an owner’s recovery, financing obligations, and ability to reopen or retain tenants.
For California commercial property owners, valuation is not a policy detail to skim past. Construction costs, labor availability, code requirements, and wildfire-driven market conditions can all widen the gap between an asset’s original cost and what it takes to rebuild it today. Strategic coverage begins with understanding what the policy is designed to pay after a covered loss.
What Replacement Cost Coverage Pays
Replacement cost coverage is generally designed to pay the cost to repair or replace covered property with materials of like kind and quality, without deducting depreciation. In plain terms, it focuses on the present-day cost of restoring the damaged building or business personal property, subject to the policy’s limits, terms, deductibles, and conditions.
Consider a 15-year-old HVAC unit damaged by a covered fire. Its resale value may be limited because of its age, but replacing it can require a significant current investment. With replacement cost valuation, the claim is intended to account for the cost of a comparable new unit rather than treating the unit as nearly exhausted simply because it is older.
For a commercial landlord, that distinction can support a more complete recovery after damage to a roof, plumbing system, electrical components, flooring, built-in fixtures, or other insured building elements. It is often the valuation approach owners prefer for properties they intend to restore and continue operating over the long term.
Replacement cost does not mean an insurer will fund unrestricted upgrades or a higher-quality project than the property had before the loss. The policy generally responds to comparable construction and may contain specific language about matching, functional replacement, valuation limits, or what happens if the building is not repaired. Review those provisions closely rather than relying on the coverage label alone.
How Actual Cash Value Changes a Claim
Actual cash value, often shortened to ACV, starts with the value of damaged property and applies depreciation. The exact method can vary by policy and jurisdiction, but the familiar concept is replacement cost minus depreciation for age, condition, obsolescence, and expected useful life.
Using the HVAC example, assume a comparable replacement costs $40,000 and the damaged unit is assessed as 60% depreciated. An actual cash value settlement could be approximately $16,000 before the deductible. The owner still faces the current replacement cost if restoring the building requires a new unit.
That gap is not limited to mechanical equipment. It may apply across the building, from roofing and carpeting to interior finishes and business personal property. An actual cash value policy can be appropriate in certain circumstances, particularly where an owner does not plan to rebuild after a loss or is insuring property with a different risk strategy. But it requires clear-eyed planning around the capital that may be needed beyond the insurance proceeds.
Actual cash value is not always calculated identically
Policy wording matters. Some policies describe ACV through replacement cost less depreciation. Others may use a broader interpretation of value. The condition of the property, local construction costs, the category of damaged items, and claim-specific facts can influence the result.
This is why sophisticated property owners should not assume that “actual cash value” has one universal formula. A policy review should identify how the carrier defines valuation, how depreciation is applied, and whether certain property categories have their own settlement provisions.
Replacement Cost Versus Actual Cash for Commercial Buildings
The most meaningful comparison is not which option sounds better in isolation. It is whether the valuation method supports the owner’s plan after a major loss.
A landlord with a stabilized retail center, office building, industrial property, or apartment complex generally has continuing obligations: loan covenants, leases, tenant expectations, income targets, and an ongoing duty to maintain a safe, usable property. If the intention is to repair promptly and preserve the asset’s long-term value, replacement cost coverage may better align with that strategy.
Actual cash value can create a larger retained financial exposure because depreciation shifts more of the rebuilding burden to the property owner. That may be manageable for a lightly improved structure, a property approaching redevelopment, or a deliberate self-insurance strategy. It may be far less workable when a loss interrupts rental income, strains lender relationships, or delays a tenant’s return.
Market value should not be confused with either measure. A building’s real estate value reflects location, occupancy, income potential, land value, and market demand. Insurance replacement cost concerns the expense to reconstruct the covered physical property. A coastal commercial property may have a market value far above its rebuild cost, while a building in another area may cost more to rebuild than its current sale price suggests. Neither circumstance automatically establishes the right insurance limit.
The Coverage Details That Can Matter Just as Much
Replacement cost valuation is a critical foundation, but it is only one part of a comprehensive property program. Several related provisions can determine whether a claim supports a full recovery.
Adequate building limits and valuation updates
A replacement cost policy can still leave an owner exposed if the building limit is too low. Construction inflation, specialized finishes, supply constraints, and regional labor costs can change quickly. California owners should periodically reassess insured values, especially after renovations, acquisitions, tenant build-outs, or material changes in construction costs.
Many commercial policies also include coinsurance provisions. These provisions may reduce a claim payment if the building was not insured to the required percentage of its replacement value, even when the loss is smaller than the policy limit. Some programs use agreed value options to address coinsurance, but those arrangements require accurate statements of value and careful renewal management.
Recoverable depreciation and repair requirements
On some replacement cost policies, an insurer may initially pay an actual cash value amount and release the recoverable depreciation after repairs or replacement are completed. This is common enough to deserve advance planning.
The policy may impose timelines, documentation requirements, and conditions for receiving the full replacement cost benefit. Owners should understand whether they have sufficient liquidity to begin restoration, how tenant obligations will be managed during repairs, and what records the claims process will require.
Ordinance or law coverage
A loss can trigger building-code requirements that did not apply when the property was originally constructed. Required upgrades may involve electrical systems, fire protection, accessibility features, energy standards, or demolition of undamaged portions needed to complete compliant reconstruction.
Standard replacement cost coverage may not fully address these added expenses. Ordinance or law coverage is often a vital complement for older buildings and properties in jurisdictions with evolving code requirements. It can help address the cost of undamaged portions, demolition, and increased cost of construction, depending on the policy structure.
Business income and extra expense
Rebuilding the structure is only part of the financial picture. A covered loss can interrupt rent, force tenants to relocate, and create continuing operating expenses. Business income and extra expense coverage may help protect the income stream and support necessary measures during restoration, subject to the terms of the policy.
For lessors, the details deserve particular attention. Lease terms, tenant mix, vacancy, indemnity provisions, and the allocation of responsibilities for tenant improvements can all influence how a loss affects the owner. Property coverage and income protection should be evaluated together rather than as separate decisions.
Questions to Ask Before Renewing or Buying Coverage
A productive review starts with the property itself: its construction type, age, square footage, systems, finishes, occupancy, and planned improvements. It should also consider the owner’s intended response to a severe loss. Will the building be rebuilt at the same location? Are there lender requirements? Would a prolonged interruption put tenant relationships or rental income at risk?
Ask whether building coverage is written on replacement cost or actual cash value, how depreciation is calculated, and whether recoverable depreciation is available. Confirm the adequacy of the building limit, the presence of coinsurance, and the scope of ordinance or law coverage. Then examine business income limits and the period of restoration with the same care given to the structure itself.
For apartment owners, it is also wise to examine whether the policy reflects common areas, amenities, laundry facilities, maintenance buildings, and property owned by the insured. For commercial landlords, clarify the division between landlord-owned improvements and tenant property. Small ambiguities before a loss can become expensive disputes afterward.
At Koda Insurance Services, we view valuation as part of a broader risk-management conversation, not a line item to select in isolation. The right approach reflects the property, the ownership structure, the tenant obligations, and the recovery plan behind the asset.
The most valuable time to resolve a replacement cost versus actual cash value question is before a fire, water loss, or other covered event puts the answer to the test. A thoughtful coverage review gives owners a clearer path forward and helps safeguard the property, income, and long-term plans they have worked hard to build.