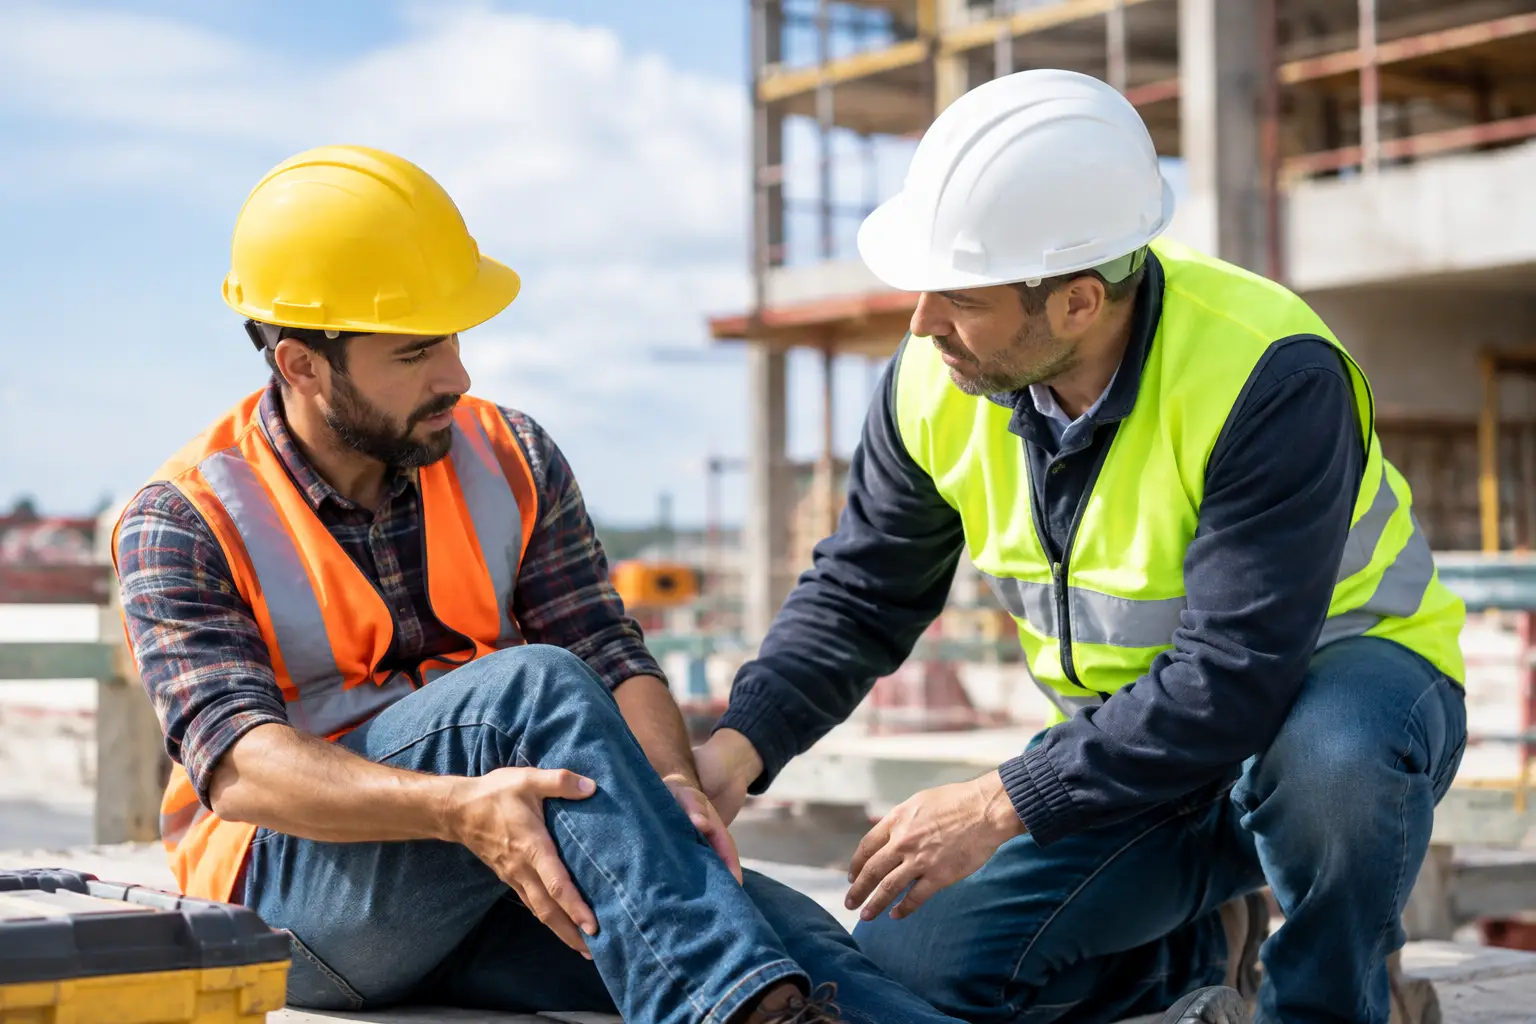
A contractor falls from a ladder while repairing the roof of your commercial building. Before anyone discusses fault, the question becomes immediate: does workers compensation cover contractors? For California business owners and property investors, the answer depends less on the label in a contract and more on the real working relationship, the contractor’s business status, and the insurance documentation in place before work begins.
Workers compensation is designed to provide medical care, wage-replacement benefits, and other statutory benefits when an employee is injured in the course of employment. It is not automatically a catch-all policy for every independent professional, vendor, or construction crew that enters your property. That distinction matters because a contractor injury can create significant operational, financial, and liability concerns when classification or coverage is unclear.
Does Workers Compensation Cover Contractors in California?
Generally, your workers compensation policy covers your employees, not truly independent contractors. A contractor who operates an independent business and carries their own workers compensation coverage for their employees should look first to that policy after a work-related injury.
The challenge is that California does not rely solely on what the parties call the relationship. If a worker is treated as an independent contractor on paper but is directed, controlled, and integrated into your business like an employee, the worker may be found to be an employee for workers compensation purposes. A claim could then involve your policy, your payroll reporting, and potentially penalties or premium adjustments.
Construction work receives especially close attention. California has specific rules that can affect the status of unlicensed contractors and workers in construction-related trades. A business owner should not assume that a signed independent contractor agreement settles the issue. Licensing, business structure, control over the work, payment methods, tools, supervision, and the ability to serve other clients can all matter.
For commercial landlords, apartment owners, and property managers, this comes up regularly during repairs, tenant improvements, landscaping, restoration work, and capital projects. The contractor may be hired directly by the owner, through a property manager, or by a tenant. Each arrangement should be reviewed with the same discipline, because the exposure can shift with the contract and the facts on the ground.
When a Contractor May Be Treated as an Employee
An independent contractor arrangement is strongest when the contractor operates an established, separate business. They typically control the means and manner of their work, provide specialized services, use their own tools, set their schedule within project requirements, and remain free to work for other clients.
Risk rises when an owner or business effectively manages the worker as staff. For example, a building owner who hires an individual maintenance worker, supplies the equipment, establishes daily hours, directs each task, and pays the person regularly may be creating an employment relationship, even if invoices describe the person as a contractor.
This is not merely an administrative concern. If that worker is injured, the business may face a workers compensation claim, uninsured exposure if no applicable policy exists, and questions regarding payroll and labor compliance. A workers compensation carrier may also review whether payments to uninsured subcontractors should have been included in the policyholder’s payroll during an audit.
The practical lesson is simple: do not use the word “contractor” as a substitute for a classification review. The financial stakes are too high for a label to carry the entire risk-management strategy.
The Contractor’s Coverage Is Not the Whole Picture
A contractor’s certificate of insurance is valuable, but it is only a starting point. It should confirm active workers compensation coverage when the contractor has employees and should match the legal name of the entity signing your agreement. A certificate that names a similar company, has expired, or does not reflect the actual scope of work offers little comfort after an accident.
For higher-risk work, such as roofing, electrical repairs, structural renovations, tree service, plumbing, or water remediation, request updated documentation before work starts and again when a project extends over time. Verify that the contractor’s general liability coverage is also active. Workers compensation addresses injuries to the contractor’s employees. General liability may respond to third-party bodily injury or property damage allegations, subject to its terms and exclusions.
Neither coverage should be viewed in isolation. If a contractor’s employee damages a sprinkler line, causes a fire, or injures a tenant or visitor, several policies and contractual responsibilities may be implicated. Well-structured insurance requirements help establish a clear path for handling a loss, but they do not eliminate the need for careful vendor selection and project oversight.
Why Commercial Property Owners Need a Contractor Protocol
Owners of office, retail, industrial, and multifamily properties often rely on a rotating group of service providers. That convenience can become a coverage gap when documentation is collected inconsistently. A technician who is properly insured for a one-time repair may later return with additional workers, perform a different scope of work, or operate under a different business entity.
A disciplined contractor protocol protects the property, the operating business, and the people who rely on both. Before work begins, confirm the contractor’s legal business name, license status when required, scope of services, and insurance requirements. Keep signed agreements and current certificates in a centralized file. For larger projects, the agreement may also need tailored provisions addressing additional insured status, waiver of subrogation, indemnification, and primary coverage obligations.
These requirements should be drafted and reviewed with qualified legal and insurance professionals because the appropriate wording depends on the project and the parties involved. A boilerplate agreement copied from an old job may not adequately protect a property owner undertaking substantial renovations or managing a habitational property with ongoing resident exposure.
Property managers should also establish clear internal boundaries. On-site staff can coordinate access and report unsafe conditions, but they should not casually direct a contractor’s employees in a way that blurs responsibility for how the work is performed. Safety expectations are appropriate. Day-to-day control over the contractor’s labor can create more complicated classification questions.
What Happens If an Uninsured Contractor Is Hurt?
The answer depends on the facts, which is why prompt reporting and professional guidance matter. If the person is a true independent contractor with no employees, their own medical coverage or other resources may initially be involved. But if the worker is determined to be your employee under California law, your business may be responsible for workers compensation benefits.
If the injured person has employees and should have maintained workers compensation coverage but did not, the consequences can be serious for both the contractor and the hiring business. Your insurer may examine the relationship, the written contract, payment records, and the degree of control exercised. The property owner may also face allegations outside the workers compensation system, depending on the circumstances and legal duties involved.
Do not try to resolve a workplace injury informally by paying medical bills directly or asking the injured person to sign a release. Early decisions can complicate a claim and may not resolve the legal obligations that follow. Report the incident promptly to the appropriate insurer, preserve relevant records, and involve counsel when warranted.
A Better Way to Manage Contractor Risk
The most effective approach is proactive and consistent. Treat contractor insurance review as part of your property and business operations, not as paperwork to gather after a loss. This is particularly valuable for California owners managing older buildings, multifamily communities, or properties exposed to wildfire, water, and construction-related risks.
Your workers compensation program should accurately reflect your own workforce, including any labor arrangements that may be questioned during an audit. Your commercial property and liability policies should be reviewed alongside contractor agreements so that protection is coordinated rather than fragmented. The right structure balances contractual risk transfer with coverage that supports your own long-term financial security.
At Koda Insurance Services, we help California business owners and property investors look beyond a certificate and consider the complete risk picture. That includes the people performing work, the assets they enter, the contracts that allocate responsibility, and the insurance that supports business continuity when something goes wrong.
A contractor relationship can be a sound business decision, but only when responsibilities are clear before the first tool is unpacked. Taking time to verify coverage, classification, and contract terms is a practical way to safeguard the property, the business, and the people who matter most.