Commercial Earthquake Insurance For Businesses And Property Owners
Earthquakes can cause extensive damage to commercial buildings, equipment, inventory and other business property—often with little or no warning. And because earthquake damage is typically excluded from standard commercial property insurance, businesses can be left with a significant coverage gap.
At Koda Insurance Services, we help businesses and commercial property owners throughout Southern California understand their earthquake exposure and explore coverage options designed around their property, assets and operations. Whether you own a commercial building, manage multiple properties or operate a business from a leased location, we’ll help you determine where earthquake insurance fits into your overall protection strategy.
Understanding Commercial Earthquake Risk
In Southern California, earthquake risk is part of doing business. A significant earthquake can damage a building’s structure, foundation and permanently installed systems while also affecting equipment, inventory, furnishings and other business property.
The financial impact can extend beyond the initial physical damage. Repairs may be substantial, access to a property may be restricted and normal business operations can be disrupted while damage is assessed and repaired.
Because earthquake damage is generally excluded from standard commercial property insurance, businesses and property owners should evaluate earthquake coverage separately as part of their overall risk-management strategy.
Who Needs Commercial Earthquake Insurance?
Commercial earthquake insurance can be an important consideration for businesses and property owners throughout Southern California, where seismic risk can vary based on location, building construction, property age and other factors.
Commercial building owners, property management companies, multifamily properties, retail businesses, restaurants, offices, warehouses and businesses with valuable equipment or inventory can all face significant financial exposure following an earthquake.
Even when earthquake insurance isn’t required, understanding your potential exposure can help identify a major gap in your commercial insurance program. The question isn’t simply whether an earthquake will happen—it’s whether your business could absorb the financial impact if it does.
Commercial Earthquake Insurance Planning
Strategic Earthquake Insurance Planning For Your Business
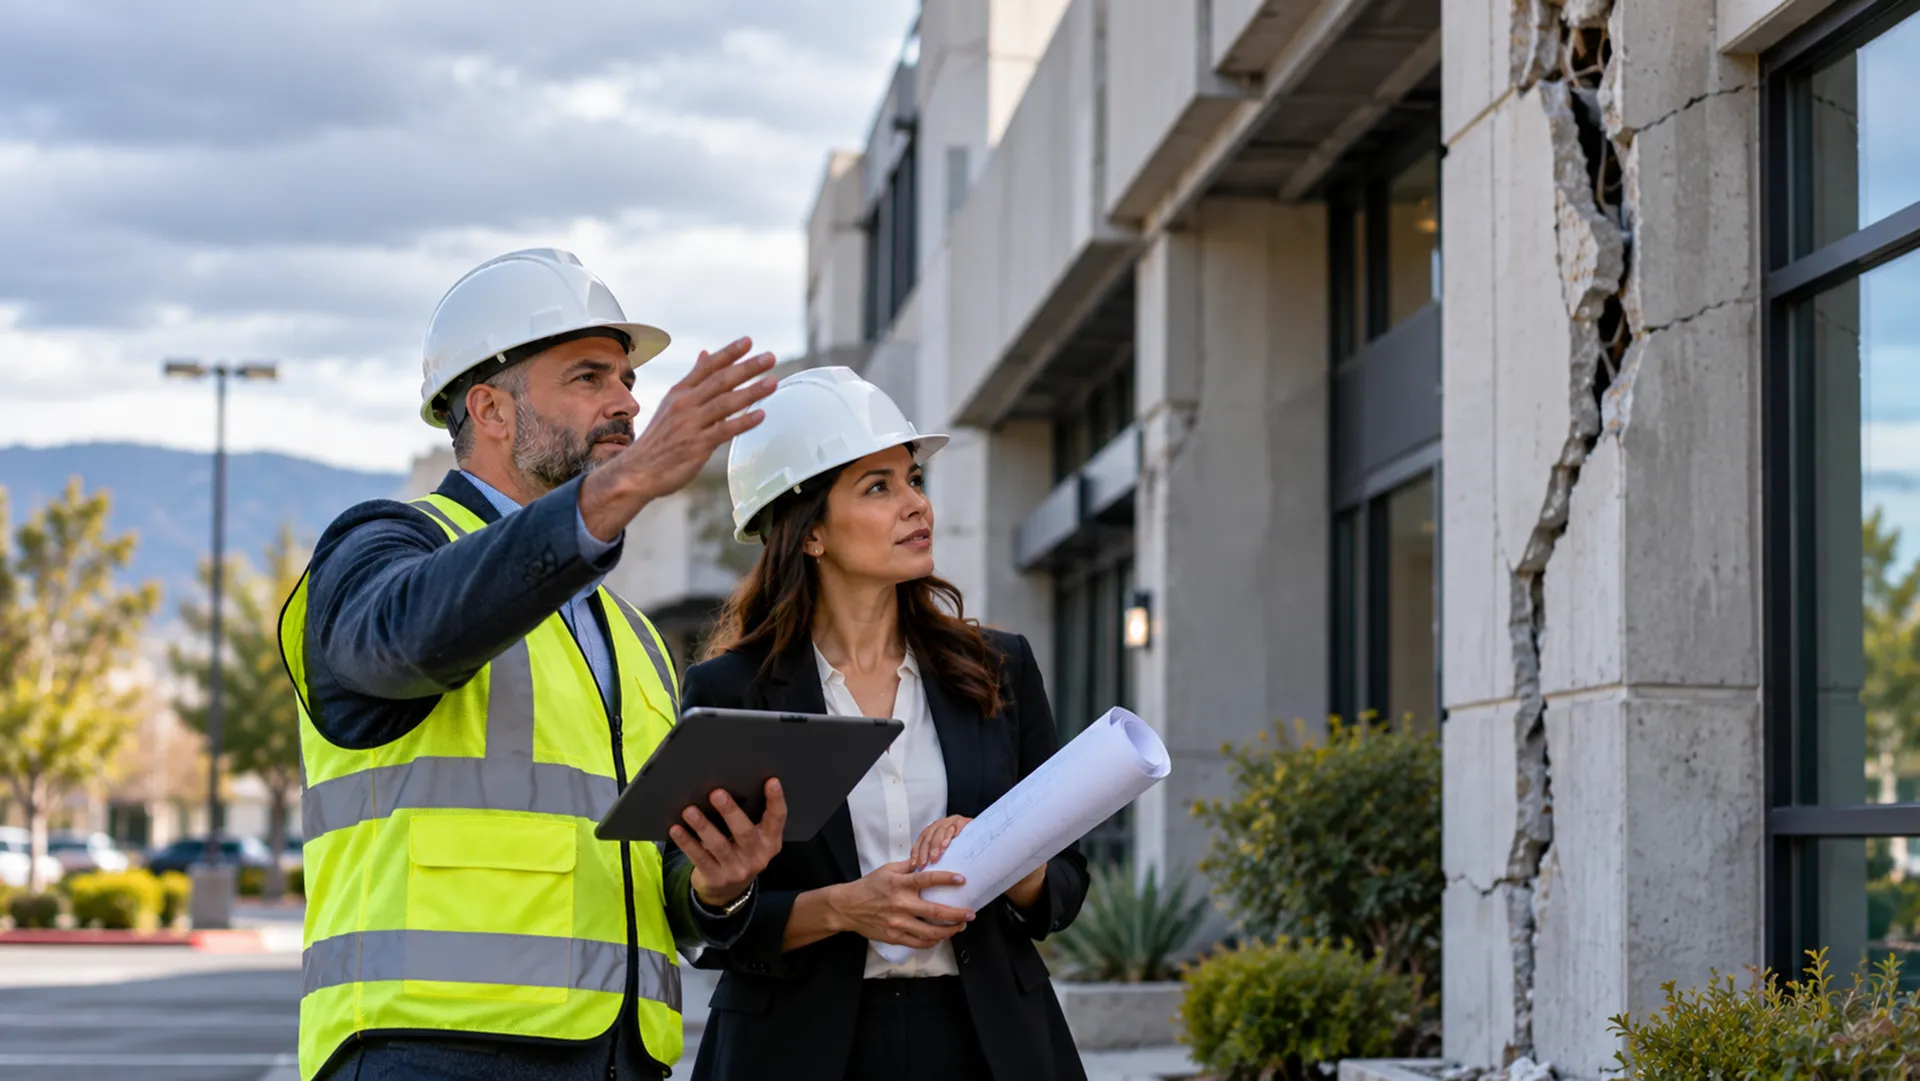
Earthquake risk isn’t the same for every commercial property. Building age and construction, location, property values, equipment and inventory can all influence both your exposure and the type of protection your business may need.
Koda Insurance Services can help you assess those factors and compare earthquake coverage options, including policy limits, deductibles and other important terms. Because earthquake policies can carry significant percentage-based deductibles, understanding your potential out-of-pocket exposure is an important part of deciding how much coverage makes sense.
The goal isn’t simply to add another policy. It’s to build an earthquake strategy that reflects the value of what you’re protecting, your business’s financial risk and your ability to recover after a major seismic event.
Free Business Insurance Checkup
Could An Earthquake Expose A Gap In Your Business Coverage?
Many businesses don’t realize standard commercial property insurance generally excludes earthquake damage until they’re reviewing coverage—or dealing with a loss.
Take our free 3-minute Business Protection Checkup to identify potential gaps in your current insurance program and get a personalized list of coverage topics to review with our expert team.
Looking for earthquake protection for your home?
Learn more about Koda’s Residential Earthquake Insurance options and visit our Earthquake Safety Checklist for practical homeowner preparedness tips